

10 min read
The Paid Traffic Truth : The Calm Week Before the Q4 Ramp
The Paid Traffic Truth — Issue 016
Published October 12,2026 * Data for the week of October 04 to October 10 2026 * Aggregated across hundreds of Wicked Reports accounts.
The Calm Week Before the Q4 Ramp
The first full week of Q4 came in quiet. The two giants are sitting within a few dollars of their September close, click prices have not started climbing, and the baseline numbers from last issue are still the baseline. One channel did not get the memo: Microsoft's new customer cost has now risen four weeks in a row.
This week's number
Meta held at $78 with 92% verified new buyers, its highest new share on record in this series, and its tightest markup over blended CAC at 8%. Google held at $163. The ramp has not arrived.
01 / Introduction
Quiet tape, one exception
Last issue closed out September and said the next structural event on the calendar was the Q4 spend ramp. This week's data says it has not started. Meta moved 1%, Google moved 2%, Meta's click prices actually fell 5%, and the auction pressure everyone is bracing for is still ahead. Quiet weeks are useful precisely because nothing is distorting the numbers.
The exception is Microsoft, covered below, followed by the same four verified grids as every week: new customer acquisition, first click versus last click, overall channel performance, and new customer lifetime value. All first-party, order-verified data aggregated across hundreds of Wicked Reports accounts. No modeling, no surveys.
02 / Analysis
Three lines, one mover
Here are the three largest paid channels over the last four weeks. Two of them are the picture of stability. One is not.
The stability is the headline, even if it does not feel like one. Meta's $78 comes with its strongest quality profile in this series: 92% of its tracked customers verified as first-time buyers and a markup over blended CAC of just 8%, meaning the number you see is almost entirely the cost of real growth. Google's $163 sits three dollars off its September close with conversion flat. Click prices are not climbing anywhere that matters yet. If you took last issue's advice and wrote down your baseline, nothing this week invalidated it, and if you did not, this is the last quiet tape you are likely to get before the ramp.
Microsoft is the counter-trend. Four straight weekly increases, $170 to $207, a 22% climb over the stretch, while its new-buyer share slid from 58% to 55% and its markup over blended CAC hit 80%, the highest of any major channel. The mechanism is murky: this week its click prices fell 4% while conversion dropped 6%, so the deterioration is in what the traffic does, not what it costs. Two honest qualifiers before anyone touches a budget. Microsoft carries 3.4% of tracked spend, so a smaller pool of accounts moves this aggregate more easily than it could on Meta or Google. And four weeks of drift in a small channel is a watch item, not a verdict. If you spend on Microsoft, the move is to pull your own verified number, not to react to the market's.
03 / New Customer Acquisition
The full acquisition picture, by channel
Beyond the headliners: YouTube keeps holding its new range, back down to $366 this week with conversion up 14% and a growing spend share at 4.3%. Five weeks ago that channel cost roughly $630 per new customer, and the reset has now held long enough to treat the low $400s and below as its current level. TikTok swung violently upward this week, which means nothing, exactly as its downward swing meant nothing last week. The AI assistant channel had a soft conversion week but remains one of the highest new-buyer shares in the set at 79%.
04 / First Click vs Last Click
Two models, two different weeks
One measurement note worth connecting to the Microsoft story above. Microsoft's last-click over-credit widened to 0.61 this week, its largest in this series, at the same time its verified new customer cost hit a four-week high. A last-click dashboard shows that channel improving while the verified grid shows it deteriorating. That is not a contradiction, it is two models answering different questions, and only one of them is pricing new customers.
05 / Overall Channel Performance
Where the money goes, and THE TRUE COST OF A NEW CUSTOMER
The Microsoft row is this grid's cautionary tale this week. It posts the best ROAS in the set at 1.70, and it carries an 80% markup between blended CAC and true new customer cost, which means most of what that ROAS is celebrating is repeat demand. A channel can look like your best performer and be your most expensive source of actual growth at the same time. Meta remains the inverse: the worst-looking ROAS at 0.55 and the cheapest verified new customer at $78.
06 / New Customer Lifetime Value
What a new customer becomes over a year
The value side gives Microsoft its fair hearing. A Microsoft new customer is the most valuable paid acquisition in the set at $373 over a year, so even at $207 the channel still pays back on its own click-credited revenue. The four-week climb has not broken its economics, it has thinned them: the spread between one-year value and acquisition cost has narrowed from roughly $195 a month ago to $166 now. The standing caveat applies: this grid blends brands at very different price points, so treat it as a directional market benchmark, not a promise for any one store.
07 / Conclusion
Use the quiet. It will not last.
The market enters mid October with the big baselines intact: Meta near $78 at the strongest new-buyer quality this series has recorded, Google near $163, YouTube settled at roughly half its summer cost, and Microsoft drifting the wrong way on thin volume. BFCM is about seven weeks out, and the auction pressure that will define November has not shown up in click prices yet.
If you recorded your baseline last week, verify it held and move on. If you did not, do it now, because every week from here adds ramp noise to the numbers you are trying to call normal. And if Microsoft is in your mix, pull your own verified nCAC and new-buyer share for the last four weeks specifically. The aggregate says that channel is getting more expensive while looking better on ROAS, and that combination is exactly how a line item earns budget it no longer deserves.
See your own version of these four grids.
Your real nCAC next to your aCAC, your first versus last click gap, your new customer LTV by channel, in your own account.
Get the Paid Traffic Truth Report directly to your inbox.
How this week's numbers were built. Aggregated across hundreds of Wicked Reports client accounts for the week of October 04 to October 10, 2026, except first click vs last click, which uses a rolling 90 day window. New versus repeat is verified at the order level against first party order IDs, not modeled and not surveyed. The new visit to new customer conversion rate credits the channel that originated the new visit. Channels without cost data, including email, SMS, organic, and influencer, are left out of the cost comparisons. Snapchat is excluded for negligible spend. Pinterest is marked with an asterisk because it ran on a small number of new customers this week, so it is not used to anchor any headline. The channel labeled Facebook in the underlying platform data is shown here as Meta. Charts and tables carry meaning through direction, labels, and contrast rather than color alone.
Topics: Wicked Reports New Customer Acquisition Cost (NCAC) Paid Traffic Truth paid media measurement BFCM Q4 Budget Planning Microsoft Ads
10 min read
The Paid Traffic Truth : Paid Traffic Enters Q4 Cheaper Than It Left August
The Paid Traffic Truth — Issue 015
Published October 05,2026 * Data for the week of September 27 to October 03 2026 * Aggregated across hundreds of Wicked Reports accounts.
Paid Traffic Enters Q4 Cheaper Than It Left August
September threw a holiday spike, a month-long Meta slide, and a YouTube reset at the market. Now the month is closed and the noise has washed out, and the net result is simple: the two channels carrying 92% of tracked spend enter Q4 at or below where they ended August. These are the baseline numbers to judge the Q4 ramp against, and the ramp is the next thing coming.
This week's number
The September round trip is complete. Meta enters October at $76, 11% cheaper than late August. Google enters at $160, flat to where it started, with the holiday spike fully unwound.
01 / Introduction
The month closed. Here is where it left you.
This is the first issue of October, so before the weekly grids, this one does something the series has not done before: it closes out a full month. Five weeks of verified data covered the Labor Day run-up, the holiday itself, two clean recovery weeks, and now the first week of Q4 proper. Every one of those weeks moved some channel around. The question that matters for planning is what survived the round trip.
The answer is below, followed by the same four verified grids as every week: new customer acquisition, first click versus last click, overall channel performance, and new customer lifetime value. All first-party, order-verified data aggregated across hundreds of Wicked Reports accounts. No modeling, no surveys.
02 / Analysis
One chart, the whole month
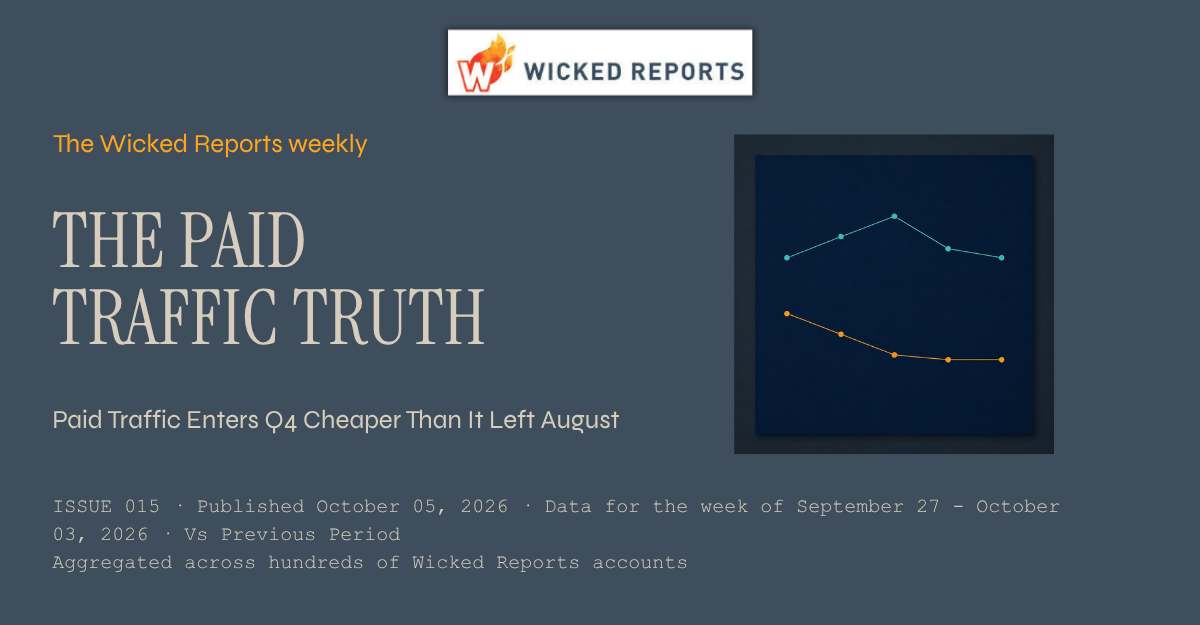
Here is September in a single picture: verified nCAC for the two largest channels, all five weeks.
Two stories ran through September, and they ended differently. Google's story was the holiday: Labor Day pushed its new customer cost from $161 to $179, and three consecutive declining weeks brought it back to $160, with conversion up 3% this week. A complete round trip. If you panicked about Google in mid September or celebrated it this week, you were reacting to the calendar both times.
Meta's story was not the holiday, and that is the part worth carrying into Q4. Its decline ran through the holiday weeks and the clean weeks alike, $85 to $74 over four weeks, before ticking up 2% to $76 this week on softer conversion. One week is a data point, not a reversal, so the honest read is that the slide has stopped and the channel has settled at a level about 11% below late August. The quality held the entire time: 91% of Meta's tracked customers are verified first-time buyers, same as every week this month, with the markup over blended CAC now at 9%. The cause of the slide is still what it was last week, a mix story rather than cheaper auctions, and still unproven. The level itself is verified either way.
Why this matters right now: the Q4 ramp is the next structural event on the calendar. As BFCM spend floods the auctions over the coming weeks, costs will climb, and every brand will face the same question at every weekly check-in: is this seasonal inflation I planned for, or is my account deteriorating? You cannot answer that without knowing precisely where you started. This month-end snapshot is the market's starting line. Yours is in your own account.
03 / New Customer Acquisition
The full acquisition picture, by channel
Beyond the two headliners: Microsoft drifted up again to $191 and has now round-tripped the holiday in the wrong direction, the one major channel entering October more expensive than it entered September. YouTube settled a second week in the low $400s, still well below its August range, with a soft conversion week. TikTok collapsed back to thin-data status with a new-buyer share that fell to 51%, its fourth violent swing in four weeks, which is exactly why thin channels never anchor a conclusion here.
04 / First Click vs Last Click
Who starts the sale vs who takes the bow
This grid is a measurement reconciliation, not an investment case. It explains why the platforms' own dashboards disagreed with the verified numbers all month: last click shifts credit from the channels that open journeys toward the channels that close them, so a last-click view understated Meta's September and flattered the search channels. When you compare your Q4 numbers against a baseline, make sure both were measured under the same model, or the comparison is meaningless before you start.
05 / Overall Channel Performance
Where the money goes, and THE TRUE COST OF A NEW CUSTOMER
The standing pattern survives the month-end accounting intact. Google's ROAS is 2.7x Meta's, and a new customer still costs 111% more there, because its 54% markup between blended CAC and true new customer cost is repeat demand doing the flattering. Meta's 9% markup is the tightest in the grid. Whatever the Q4 auctions do to these numbers, the ROAS column will keep ranking the channels in the wrong order for growth, and that does not change with the season.
06 / New Customer Lifetime Value
What a new customer becomes over a year
The value side barely moved all month, which is the point of this grid. Acquisition costs swung with the calendar while what a new customer becomes stayed steady: Meta's one-year value sat within a few dollars of $108 every week, Google's near $243. That stability is what makes the cost side plannable. Your Q4 question is not whether customers will be worth less, it is what you will pay to get them. The standing caveat applies: this grid blends brands at very different price points, so treat it as a directional market benchmark, not a promise for any one store.
07 / Conclusion
Write down your starting line this week
The market enters Q4 with Meta around $76 and 11% cheaper than late August, Google flat at $160, Microsoft slightly elevated, and YouTube settled well below its summer range. Clean entry conditions, about eight weeks out from BFCM, with the spend ramp ahead of it.
The move this week takes twenty minutes. Pull your own verified September numbers per channel, nCAC and new-buyer share, and write them down as your Q4 baseline before October data starts piling on top of them. Then judge every week of the ramp against that line. When your Meta nCAC reads 30% higher in early November, the baseline is what tells you whether that is the seasonal inflation everyone pays or a problem that is yours alone. Brands that skip this step spend November arguing about numbers nobody wrote down in October.
See your own version of these four grids.
Your real nCAC next to your aCAC, your first versus last click gap, your new customer LTV by channel, in your own account.
Get the Paid Traffic Truth Report directly to your inbox.
How this week's numbers were built. Aggregated across hundreds of Wicked Reports client accounts for the week of September 27 to October 03, 2026, except first click vs last click, which uses a rolling 90 day window. New versus repeat is verified at the order level against first party order IDs, not modeled and not surveyed. The new visit to new customer conversion rate credits the channel that originated the new visit. Channels without cost data, including email, SMS, organic, and influencer, are left out of the cost comparisons. Snapchat is excluded for negligible spend. Pinterest is marked with an asterisk because it ran on a small number of new customers this week, so it is not used to anchor any headline. The channel labeled Facebook in the underlying platform data is shown here as Meta. Charts and tables carry meaning through direction, labels, and contrast rather than color alone.
Topics: Wicked Reports New Customer Acquisition Cost (NCAC) Meta Ads Paid Traffic Truth paid media measurement BFCM Q4 Budget Planning
10 min read
The Paid Traffic Truth : Why Meta's New Customer Cost Fell Four Weeks Straight
The Paid Traffic Truth — Issue 014
Published September 28,2026 * Data for the week of September 20 to September 26 2026 * Aggregated across hundreds of Wicked Reports accounts.
Meta Got Cheaper Four Weeks in a Row
September's noise was the holiday. September's signal was Meta. While the other channels bounced around Labor Day and back, the verified cost of a new customer on Meta fell every single week of the month, and it is doing it with the highest share of genuinely new buyers of any channel. If you are setting Q4 budgets on last quarter's Meta numbers, they are already stale.
This week's number
Meta's verified nCAC fell a fourth consecutive week to $74, down from $85 a month ago, a 13% decline at a steady 91% new-buyer share.
01 / Introduction
The quietest trend of the month is the biggest one
For three issues running, Meta's falling new customer cost has been a side note while louder stories took the headline. It has now earned the headline. Four weeks, four declines: $85, $82, $78, $74. On the channel carrying half of all tracked spend in this data set, that is not a footnote. That is the market moving.
This issue looks at what is behind the run and what it should change about Q4 planning, then walks the same four verified grids as every week: new customer acquisition, first click versus last click, overall channel performance, and new customer lifetime value. All first-party, order-verified data aggregated across hundreds of Wicked Reports accounts. No modeling, no surveys.
02 / Analysis
Four weeks down, and the new-buyer share never budged
A falling acquisition cost is only good news if the customers are real. The first thing I checked across all four weeks is the quality of what Meta is delivering, and it held. The share of Meta's tracked customers who are verified first-time buyers stayed at 90% to 91% the entire month, the highest of any channel, and the markup between blended CAC and true new customer cost stayed pinned at 10% to 11%. The decline is not repeat buyers sneaking into the mix and dragging the average down. Meta is buying genuinely new customers, and the price keeps dropping.
The holiday question is the obvious objection, and the chart answers it. The first two declines happened during the Labor Day run-up and the holiday week itself, when discovery channels always get a temporary discount, and I said at the time not to treat that cheapness as a baseline. But the holiday unwound weeks ago. Search costs snapped back. Meta kept falling anyway, through two clean weeks, which is what separates a calendar effect from a trend.
What I cannot yet give you is the cause. This week's decline came with conversion nearly flat and click prices nearly flat, so the drop is not better auction prices and not better site conversion. That points to mix: which accounts, campaigns, and products the spend is flowing through. One candidate worth naming is that Meta's share of tracked spend has drifted down for three straight weeks, from 53.5% to 50.1%, and when marginal dollars leave a channel, the budget that remains tends to be concentrated in its strongest campaigns, which improves the average. That is a hypothesis, not a finding. The trend is verified. The mechanism is not, and I would rather tell you that than invent a clean story.
03 / New Customer Acquisition
The full acquisition picture, by channel
Elsewhere in the grid: Google settled a second week at $167 with conversion up 4%, so search is back to its normal shape after the holiday. YouTube gave back part of last week's big drop, landing at $430 with 76% new buyers, still well below its August range of roughly $800, and worth continued attention. Microsoft had an odd week, with conversion up 5% but click prices up 9%, pushing its nCAC to $186. TikTok whipsawed downward again and returns to thin-data status, which is why I do not trade on its weekly reads.
04 / First Click vs Last Click
Who starts the sale vs who takes the bow
The Meta row is the reason a month-long trend like this stays invisible on most dashboards. Meta is under-credited on last click, so a chunk of the new customers it keeps acquiring more cheaply gets booked to whatever search ad closed the journey. If your reporting runs on last click, your Meta improved all month and your dashboard split the credit with Google.
05 / Overall Channel Performance
Where the money goes, and THE TRUE COST OF A NEW CUSTOMER
The standing pattern holds even in Meta's best month. Google posts a ROAS of 1.32 against Meta's 0.51, and a new customer still costs 126% more on Google. The 56% markup between Google's blended CAC and its true new customer cost is repeat demand doing the flattering. Meta's 10% markup means the cheap number on its row is almost entirely new business. If Q4 budgets get set on the ROAS column, the money moves in exactly the wrong direction.
06 / New Customer Lifetime Value
What a new customer becomes over a year
The LTV grid shows why the four-week run matters more than a discount usually would. Meta has always been the thin-margin channel in this data set: a low first order that grows to $108 at one year, against an acquisition cost that used to leave little room. A month ago that spread was $111 of value against $82 of cost. This week it is $108 against $74. Same value curve, meaningfully more margin. The standing caveat applies: this grid blends brands at very different price points, so treat it as a directional market benchmark, not a promise for any one store.
07 / Conclusion
Re-pull your Meta number before you lock Q4
Black Friday budgets are being finalized right now, and most of them are being built on Meta nCAC assumptions from July or August. This data says the market's number has moved 13% in a month. If your plan still carries the old figure, your Q4 model is conservative in the one place you might not want it to be, and if you are pacing spend to a target nCAC, you may be leaving volume on the table at a price you would happily pay.
The move this week: pull your own verified Meta nCAC for September, not the platform-reported number, and check it against whatever figure is sitting in your Q4 plan. Then check your new-buyer share alongside it, because a cheap Meta number only helps if it is buying new customers rather than recycling old ones. The aggregate trend is real, but your account is not the aggregate, and the only version of this number worth planning on is your own.
See your own version of these four grids.
Your real nCAC next to your aCAC, your first versus last click gap, your new customer LTV by channel, in your own account.
Get the Paid Traffic Truth Report directly to your inbox.
How this week's numbers were built. Aggregated across hundreds of Wicked Reports client accounts for the week of September 20 to September 26, 2026, except first click vs last click, which uses a rolling 90 day window. New versus repeat is verified at the order level against first party order IDs, not modeled and not surveyed. The new visit to new customer conversion rate credits the channel that originated the new visit. Channels without cost data, including email, SMS, organic, and influencer, are left out of the cost comparisons. Snapchat is excluded for negligible spend. Pinterest is marked with an asterisk because it ran on a small number of new customers this week, so it is not used to anchor any headline. The channel labeled Facebook in the underlying platform data is shown here as Meta. Charts and tables carry meaning through direction, labels, and contrast rather than color alone.
Topics: Wicked Reports New Customer Acquisition Cost (NCAC) Meta Ads Paid Traffic Truth paid media measurement Q4 Budget Planning Verified Attribution
10 min read
The Paid Traffic Truth : Why Holiday Demand Pays Meta and Bills Google
The Paid Traffic Truth — Issue 012
Published September 14,2026 * Data for the week of September 06 to September 12 2026 * Aggregated across hundreds of Wicked Reports accounts.
The Holiday Kept Paying Meta and Kept Billing Google
Last week I told you the Labor Day run-up made discovery channels cheaper and search more expensive. This week contained the holiday itself, and the split did not soften. It widened. If you run both Meta and Google, the same calendar event just moved your two biggest channels in opposite directions for the second week in a row.
This week's number
Google's verified new customer cost climbed a second straight week, up 11% to $179, while Meta's fell again to $82. Same holiday. Opposite bills.
01 / Introduction
Labor Day, part two. The split held.
In Issue 011 I flagged that the Labor Day run-up was making everyone's ads look smarter than they are, with one exception : Google, the lone major channel where the cost of a new customer went up while everything else got cheaper. I also said this week's data would contain the holiday weekend itself, so we would find out whether that was noise or a pattern.
It was a pattern. This issue tells that one story, then walks the same four verified grids we publish every week: new customer acquisition, first click versus last click, overall channel performance, and new customer lifetime value. All of it is first-party, order-verified data aggregated across hundreds of Wicked Reports accounts. No modeling, no surveys.
02 / Analysis
Holiday demand is discovery demand. Two weeks of receipts.
Here is what the week of the holiday itself did to the two channels that carry 93% of tracked spend. Meta's verified nCAC fell 4% to $82, with new visit to customer conversion up 7% and click prices down 6%. Google's nCAC rose 11% to $179, with conversion down 5% and click prices barely moving. That is the second consecutive week the two lines have moved apart.
The mechanism is the one I named last week, now with confirmation. A holiday puts people in browse mode. Feeds fill with deal creative and shoppers buy things they were not searching for, which is why Meta converted better and got cheaper. Search works the opposite way. Holiday buyers who would have typed a brand name into Google got intercepted upstream by a feed ad, so search traffic skewed toward comparison shoppers and its conversion slipped. Microsoft, the other search channel in the set, told the same story louder: conversion down 13% and nCAC up 26% to $171. When both search channels move together against both discovery patterns, that is not one platform having a bad week. That is demand changing shape.
The honest note. This is still a calendar story, not a structural one. Two weeks of divergence is a holiday arc playing out exactly as a holiday arc should: the run-up week, then the holiday week itself. The structural part is the lesson, not the numbers. Holiday demand reliably flows to discovery channels and drains search, and it will do it again in November, at much larger dollar amounts. Do not read Google's $179 as its new baseline, and do not read Meta's $82 as your media buyer's genius. Next week's data should show the give-back, and I will report it either way.
03 / New Customer Acquisition
The full acquisition picture, by channel
Two things beyond the headline. Meta is running 90% new customers, the highest new share of any major channel, which means its cheap acquisition really is acquisition and not repeat business dressed up. And the search-side softness was not just Google: Microsoft's conversion fell harder than anyone's. TikTok gave back its recent volume and returns to thin-data status this week, so I am not reading anything into its swing.
04 / First Click vs Last Click
Who starts the sale vs who takes the bow
This grid explains why holiday weeks fool last-click reporting. The discovery channels that start the sale, Meta especially, are under-credited on last click, while both search channels are over-credited because they close journeys the feed started. In a week where feeds did the heavy lifting, your last-click dashboard handed even more of Meta's holiday work to Google. If you rebalanced budget off that view this week, you rewarded the closer and cut the opener.
05 / Overall Channel Performance
Where the money goes, and THE TRUE COST OF A NEW CUSTOMER
Note the standing trap in this grid. Google still posts nearly 3x Meta's ROAS, and it is still the more expensive place to buy a new customer, by 118% this week. Search ROAS is inflated by closing credit and repeat purchases; Meta's 11% markup between aCAC and nCAC says almost everything it acquires is genuinely new. If you allocate on ROAS alone, this week you would have shifted holiday budget toward the channel whose new customer cost just climbed twice.
06 / New Customer Lifetime Value
What a new customer becomes over a year
The LTV grid is why the holiday split matters beyond one week. A Google new customer is worth $241 at one year against a $179 acquisition cost, so search can absorb some holiday inflation and still pay back. A Meta customer at $111 against $82 is a thinner margin that depends on that cheap nCAC holding. One standing caveat: this grid blends brands at very different price points, so treat it as a directional market benchmark, not a promise for any one store.
07 / Conclusion
Tag both weeks, then wait for the give-back
Two weeks of Labor Day data now say the same thing. Holiday demand flows to discovery and drains search, and last-click reporting hides it by handing the feed's work to the search box. If your Meta looked brilliant and your Google looked broken these two weeks, neither is true. The calendar did both.
The move this week is bookkeeping, not budget. Tag Aug 30 through Sep 12 as holiday-affected in whatever you use to judge performance, benchmark them against past holiday windows instead of ordinary weeks, and write down what your verified nCAC did on each channel. That note is your playbook for Black Friday, when this exact pattern returns with ten times the money on the table. Next issue we find out how much of this snaps back. your own version of these four grids
See your own version of these four grids.
Your real nCAC next to your aCAC, your first versus last click gap, your new customer LTV by channel, in your own account.
Get the Paid Traffic Truth Report directly to your inbox.
How this week's numbers were built. Aggregated across hundreds of Wicked Reports client accounts for the week of September 06 to September 12, 2026, except first click vs last click, which uses a rolling 90 day window. New versus repeat is verified at the order level against first party order IDs, not modeled and not surveyed. The new visit to new customer conversion rate credits the channel that originated the new visit. Channels without cost data, including email, SMS, organic, and influencer, are left out of the cost comparisons. Snapchat is excluded for negligible spend. Pinterest is marked with an asterisk because it ran on a small number of new customers this week, so it is not used to anchor any headline. The channel labeled Facebook in the underlying platform data is shown here as Meta. Charts and tables carry meaning through direction, labels, and contrast rather than color alone.
Topics: Wicked Reports New Customer Acquisition Cost (NCAC) Paid Traffic Truth paid media measurement paid traffic attribution Holiday Demand
9 min read
The Paid Traffic Truth : The ROAS Trap Held a Second Week — and Got Wider
The Paid Traffic Truth — Issue 004
Published July 20,2026 * Data for the week of July 12 to July 18 2026 * Aggregated across hundreds of Wicked Reports accounts.
We said the ROAS trap was structural. A week later, the gap got wider
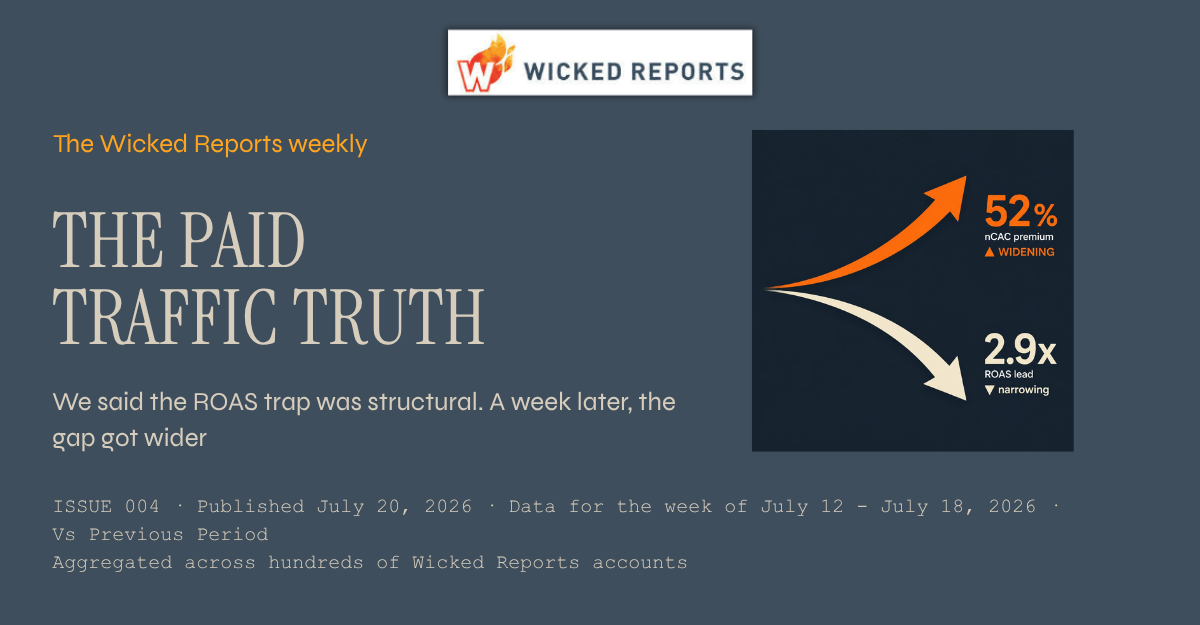
Last week I told you the ROAS trap was structural, not a July 4 hangover, and that it would look the same seven days later. It did. The only thing that changed is the gap got wider. Google's new customer went from 39% more expensive than Meta's to 52% more, while Google's ROAS lead over Meta actually shrank.
This week's number
Google's new customer cost 52% more than Meta's this week, up from 39% last week. In the same seven days, Google's ROAS lead over Meta narrowed from 3.1x to 2.9x. The two numbers are moving in opposite directions.
01 / Introduction
A follow up, because the data asked for one
Welcome to the fourth edition of the Paid Traffic Truth. Normally I bring you a new story each week. This week the data made me do something different and more useful. It let me check my own homework.
Last week's story was that ROAS ranks your channels backwards, because it fuses the cost of a new customer with the value of that customer and hides both. I said that pattern was structural, not a holiday artifact and that it would still be true after the July 4 noise cleared. This is the week that noise cleared. So let's see if it held. Every number below is first party and order verified, aggregated across hundreds of ecommerce brands.
02 / Analysis
It held. And the trap got more expensive.
Here is the honest test. If last week's ROAS trap were a July 4 mirage, this week it would soften. Search would stop looking artificially efficient, Meta would stop looking artificially weak, and the gap between reported ROAS and true new customer cost would close.
The opposite happened. Meta held the cheapest new customer in the set at $84, exactly where it was last week. Google's new customer climbed from $117 to $128. So the premium you pay for a new customer on Google, the channel that looks better on ROAS, went from 39% to 52% in one week. Microsoft, still the best ROAS in the set at 2.32, saw its new customer cost jump to $161, a 73% markup over its own blended number, up from 64%.
Sit with what that means for a budget decision. If you had watched the ROAS column last week and moved money toward Google, this week that channel's ROAS advantage got smaller and the price you paid for each new customer got bigger. You would have chased a lead that was closing while paying a premium that was rising. ROAS pointed you one way. The truth walked the other.
Here is the calendar check, because this report only works if I am honest about it. Last week you could have accused me of July 4 residue. This is the second full week clear of the holiday. The pattern did not fade, it sharpened. Two clean weeks, same direction, wider gap. That is the definition of structural. Search and Microsoft close demand and read high on ROAS. Meta prospects and reads low. It is not seasonal, and it will not fix itself.
03 / New Customer Acquisition
The full acquisition picture, by channel
Meta held its new customer cost flat at $84 and stayed the prospecting engine, with 90% of the customers it touched brand new. Google's cost rose while its new customer volume and conversion both slipped. That is the shape of the whole story in one row. The cheap acquisition channel held, the expensive one got more expensive. Pinterest ran on a tiny base again this week and carries an asterisk, so it is not anchoring anything.
04 / First Click vs Last Click
Who starts the sale vs who takes the bow
This is the engine under the trap, and it barely moved, which is the point. Last click, the model closest to what the platforms report, still inflates Google and Microsoft, the channels that close, and still shrinks Meta, the channel that opens. Meta gives back 0.14 of ROAS on last click. Microsoft gains 0.66. A rolling 90 day window does not swing on a holiday, and it did not. The credit is being handed to the closer, week in and week out.
05 / Overall Channel Performance
Where the money goes, and THE TRUE COST OF A NEW CUSTOMER
Meta and Google are again about 94% of tracked spend, so read those two rows together. Google's ROAS slipped from 1.59 to 1.43 while its new customer cost rose from $117 to $128. Both moved against you at once, and ROAS only showed you one of them. The markup column tells the same story it told last week, only louder. The gap between blended and true new customer cost is widest exactly where ROAS looks best. Microsoft's 73% markup is the cleanest example in the set.
06 / New Customer Lifetime Value
What a new customer becomes over a year
The value grid is the piece that keeps the story honest. Meta is the cheapest new customer to acquire and the lowest one year value at $97. Microsoft is the most expensive to acquire and the highest one year value at $365. This is why the answer is never simply buy Meta and cut Google. The point is that cost and value are two separate facts, and ROAS shows you neither. One caveat that always applies here. This blends hundreds of brands at different price points, so read it as a directional market benchmark, not a promise for your store.
07 / Conclusion
A pattern that survives a second week is a pattern you budget around
One week of a surprising number is a curiosity. Two clean weeks of the same number, moving further in the same direction, is a pattern. The ROAS trap is not a July 4 story and it is not going to correct itself, because it is built into how the models assign credit. The closer gets the bow. The opener gets cut.
You do not fix this with a better dashboard. You fix it with two verified numbers standing next to each other, the cost of a new customer and the value of that customer over time. Watch those instead of ROAS and the budget decision stops moving against you.
How this week's numbers were built. Aggregated across hundreds of Wicked Reports client accounts for the week of July 12 to July 18, 2026, except first click vs last click, which uses a rolling 90 day window. New versus repeat is verified at the order level against first party order IDs, not modeled and not surveyed. The new visit to new customer conversion rate credits the channel that originated the new visit. Channels without cost data, including email, SMS, organic, and influencer, are left out of the cost comparisons. Snapchat is excluded for negligible spend. Pinterest is marked with an asterisk because it ran on a small number of new customers this week, so it is not used to anchor any headline. The channel labeled Facebook in the underlying platform data is shown here as Meta. Charts and tables carry meaning through direction, labels, and contrast rather than color alone.